And just like that, mortgage rates are back under immense pressure thanks to a hotter-than-expected inflation report.
As I pointed out yesterday, CPI was the big one to watch this week, and it didn’t go the way mortgage shoppers wanted.
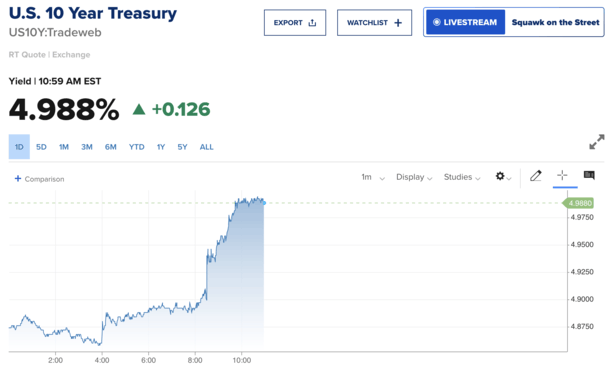
The 10-year Treasury yield jumped 12 basis points to around 4.99%, which is a huge move for one morning.
Long story short, inflation isn’t dead yet and now the Fed is under even more pressure to hike, and potentially hike 50 bps!
The result will be markedly higher mortgage rates today, likely back to around 7.25% or 7.30%, up from about 7.15% on Friday.
October CPI Cooled From September, But Still Came In Above Forecast
Consumer prices rose 0.4% in October versus the 0.3% economists had expected, per the U.S. Bureau of Labor Statistics.
While slower than September’s 0.6% increase, it was still bad news for bonds, which hate inflation.
In addition, core CPI, which strips out volatile food and energy prices, rose 0.3%, also above the 0.2% economists were looking for.
That was the third month in a row at 0.3%, and that has the bond market (and the Fed) concerned that more hikes are needed.
Something I’ve mentioned a lot in the past is that one report isn’t enough to make a trend, but now that we’ve got three in a row, it begins to look like a pattern.
[Compare mortgage rates and monthly payments side by side with my mortgage rate calculator.]
Is a 50-Basis Point Fed Rate Hike In the Cards Now?
Shortly before the report was released, Fed Governor Christopher Waller said that if core CPI came in at 0.3%, he’d support a half-point hike in December.
Most were expecting a 25-bp hike next month and it was largely baked in. But now there’s a possibility the Fed gets more aggressive.
Of course, the odds of that 50-bp hike remain very low, for now.
At last glance, CME FedWatch put it at just 11.7%, while a 25-bp hike is currently 88.3%.
Still, a 50-bp hike wasn’t even on the table before the CPI report was release, which would explain why bond yields are back near 5% again.
The Fed doesn’t set mortgage rates, but when the market expects more hikes, bond investors demand higher yields, and mortgage rates follow bond yields up.
Whether the Fed hikes that much or not, it’s a major setback for mortgage rates, which had enjoyed a really good spell over the past month.
In fact, they were inching closer and closer to a 6-handle again before we got a hot jobs report Friday and hot CPI today.
Was the Recent Drop in Mortgage Rates Just a Head Fake?
The average 30-year fixed fell from a rate of around 7.625% in early October to nearly 7.125% last week thanks to a combination of a tech selloff and cheaper oil prices.
Things were clearly trending lower and it almost appeared like the worst was behind us, yet again.
It really seemed like we could have moved even lower this week and beyond, but today’s CPI report had other ideas.
I always say nothing moves in a straight line, especially mortgage rates, so maybe it’s just the expected ebb and flow.
The worry though is this latest CPI report could be the start of another uptrend in rates, especially if odds rise for a 50-bp hike next month.
You start to wonder where the relief will come from if tech already sold off and the war is relatively clam.
As always, keep an eye on the economic data as it’s released, and another eye on the Middle East conflict.
Lastly, watch the stock market to see if the tech rout ratchets up again or cools off for the year.
If we get another flight to safety, that could help mortgage rates move lower, though it might be less impactful thanks to this latest inflation report.
(photo: atramos)
- Hot CPI Report Sends Mortgage Rates Surging Higher - November 10, 2026
- Oil Prices Keep Sinking, But Mortgage Rates Aren’t Getting Much Help - November 9, 2026
- What Happens to Mortgage Rates Post Midterms? - November 4, 2026