Well, what we didn’t want to happen, happened.
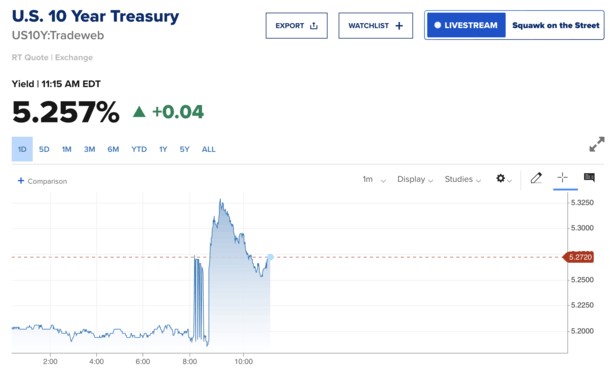
We got a hotter-than-expected CPI report this morning, sending bond yields surging higher.
After three straight days of slightly-better mortgage rates, there was some real promise we could make a more meaningful move back toward the low-7s.
But alas, the 10-year yield is about 5 bps higher today, which should put the 30-year fixed back above 7.50% if it holds.
The semi-good news is the initial reaction to the report was a lot worse, with yields up over 10 bps, so perhaps it’s not as bad as it seems.
Hot CPI Report Puts a Stop to the Mortgage Rate Rally
Inflation rose to 3.7% in September, up from 3.4% in August, a bit higher than the 3.6% economists had expected.
A lot of it boiled down to higher gas prices, which jumped more than 9% last month and accounted for over half of the monthly increase.
The bond market has already priced that in for the most part, so it wasn’t what moved yields (and rates) today.
The problem was the core number, which strips out food and energy.
It also increased 0.3% on the month, above the 0.2% economists were expecting, pushing this YoY numbers to 2.7%, also above the 2.6% expected.
While it might not sound like much, it could signal that inflation is creeping in to other areas of the economy.
Remember, oil and gas touch just about everything, not just our gas prices.
Shelter Inflation Piles More Bad News onto Housing
Within that core number we also saw shelter costs rise 0.4%, the fastest monthly pace in five months.
Shelter is one of the biggest components of CPI, and it had been slowing for more than three years, so this is yet another setback.
It’s feeling like 2023 again with mortgage rates well above what most existing homeowners have locked in.
High market mortgage rates relative to rate on existing loans keep homeowners locked into their properties, unable or unwilling to sell.
This keeps inventory low and housing costs elevated, spilling over into inflation, which ironically can keep mortgage rates higher as well!
At the same time, more people must continue renting because buying a home becomes too expensive.
That means they’re renewing leases, potentially at a higher monthly rate, and rental supply goes down, also putting upward pressure on rents.
Are Fed Rate Hikes Back on the Table?
In truth, they were never off the table really.
But now they might be on the table as soon as the October meeting in two week’s time.
The odds of a hike at the Fed’s October 27-28 meeting just about doubled after the report, climbing from 22% a day earlier to 42% this morning, per CME FedWatch.
The Fed already raised rates last month and has warned that more hikes could be needed if inflation doesn’t cooperate.
But they noted that they could be patient, and that the hikes might not be in consecutive meetings.
This report could change that if they feel it necessary to attack inflation more aggressively.
It’s also the last look at consumer prices before the all-important midterm elections, with inflation now outpacing wage growth for six months in a row.
Not exactly the data the President wanted to see, which if it had gone the other way could have been a positive talking point for Trump.
Is the Lower Mortgage Rate Trend Over Now?
I wouldn’t say it’s over, but this is certainly a setback.
As I said yesterday, I was hesitant to call it a downtrend, and today’s unwelcome news illustrates why.
We basically needed perfection on the data front to keep mortgage rates moving lower.
Instead we got a miss. We’ll get more data tomorrow with producer prices, retail sales, and jobless claims, so that could change things.
And the drop in yields after the initial surge is somewhat promising too.
The 10-year bond yield is only up about 4-5 bps this morning after being up as much as 15 bps or so.
In other words, there still might be that wall of resistance with bonds looking attractive to investors at current yields.
Of course, that doesn’t necessarily mean that mortgage rates drop from here. It just means they don’t push even higher well beyond their recent highs.
Read on: Compare different mortgage rates fast with my mortgage rate calculator.
- Mortgage Rate Winning Streak Comes to an End - October 14, 2026
- Mortgage Rates Move Lower as Oil Prices Cool Ahead of CPI Report - October 13, 2026
- Mortgage Rates Face Big CPI Report This Week - October 12, 2026