The Federal Reserve is almost guaranteed to hike rates today.
Odds are currently around 93%, per CME FedWatch, meaning it’s basically a sure thing.
In the Fed’s history, they’ve never defied odds like that so a ¼-point hike should be delivered as expected.
The impact on mortgage rates is less certain, as it always is because the Fed only deals with short-term rates.
But it wouldn’t shock me to see some relief for mortgage rates today, though the longer-term picture will remain data-driven as always.
Will the Fed Hike Lower Mortgage Rates?
First off, let’s quickly dispel the myth that the Fed sets mortgage rates. They don’t. They only set their overnight lending rate between banks.
This means if the Fed hikes, mortgage rates don’t automatically go up.
Similarly, if they cut, mortgage rates don’t automatically go down.
The only DIRECT impact on home lending is HELOCs, which are tied to the prime rate and do go up or down depending on a rate or hike of the federal funds rate (which correlates 100% with the prime rate).
So if you have a HELOC, it will likely rise by 0.25% because of today’s FOMC decision.
The good news is 0.25% shouldn’t affect the payment too deeply, though it’s still another blow with everything seemingly more expensive every day.
Now let’s talk about how the Fed does impact mortgage rates. It does so via Fed rate expectations.
The mortgage rate market reacts to what it thinks the Fed might do over time.
So if MBS investors think we’re entering a tightening cycle, they might demand higher yields (interest rates) as time goes on.
However, this isn’t a perfect science and it typically takes place before the actual Fed decision, not on the day of.
Fed Moves Often Counter Mortgage Rate Moves
This explains why mortgage rates and Fed rate hikes/cuts can diverge and often do.
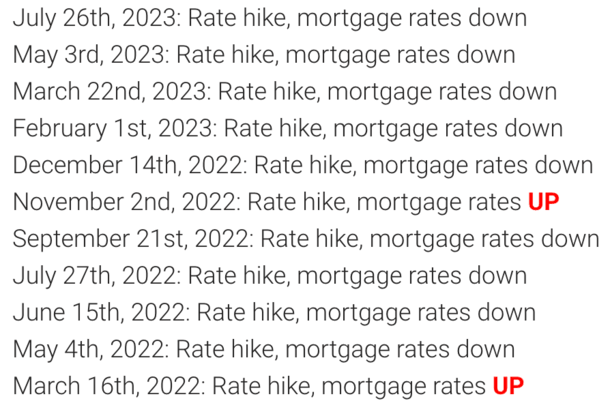
In fact, on the day of many of the most recent Fed rate decisions, mortgage rates went the other way.
I pointed this out when they were hiking back in 2022-2023.
During that tightening cycle, the Fed hiked 11 consecutive times. It was painful for the economy and for mortgage rates, which also increased from sub-3% to as high as 8%.
However, that had more to do with the end of QE (the MBS buying program) and inflation than it did the Fed raising its overnight rate.
Interestingly, on nine of those 11 days, mortgage rates actually fell. So the Fed hiked, and mortgage rates went down!
While that might seem bizarre, especially when so many wrongly believe the Fed sets consumer mortgage rates, it makes perfect sense.
Remember, the market front-runs Fed decisions because they’re so obvious and telegraphed.
So when the actual news gets delivered, it’s often just a relief valve going off.
Similarly, when the Fed cuts, the market has already made its move lower. Mortgage rates go down in anticipation, often weeks before, so there isn’t another move lower on cut day.
Instead, mortgage rates may actually move higher on a cut day!
The Underlying Economic Data Matters Most, As Usual
Ultimately, it’s the underlying economic data that matters most, as it always does.
The Fed just works off this data, whether it’s the monthly jobs report or the PCE report (inflation gauge).
They aren’t really coming up with their own decisions independent of this data.
They are making monetary policy decisions based upon this data.
This means if you want to know which direction mortgage rates will go, simply follow the data.
As a rule of thumb, if the economy/prices are cooling, mortgage rates tend to go down.
If the economy is heating up (prices rising), mortgage rates tend to go up.
It’s pretty much as simple as that.
Aside from the seemingly foregone conclusion of a 1/4-point rate hike today, there is also the press conference with Fed chair Kevin Warsh today.
What he says also has the power to move mortgage rates, though again, it will all depend on the underlying economic data. And he will say as much.
(photo: k)
- What Will Today’s Fed Rate Hike Mean for Mortgage Rates? - September 16, 2026
- Is Chase’s Mortgage Rate Sale a Good Bet on Lower Interest Rates in the Near Future? - September 15, 2026
- Mortgage Rates Are Now 1% Higher Than They Were a Year Ago - September 14, 2026