Every day, we fret about small changes in mortgage rates, even if it amounts to just a handful of basis points.
The 30-year fixed climbed from 7.17% to 7.22%! Oh no!
Meanwhile, there are lenders out there offering the same loan for nearly one full percentage point higher.
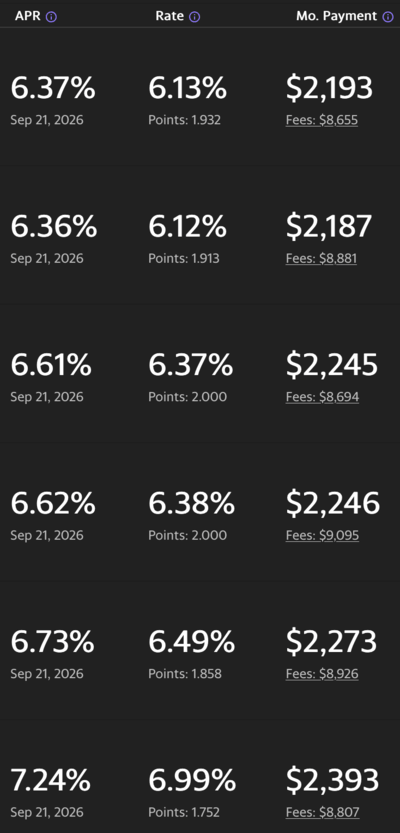
Some lenders are offering a rate of 6.125%, while others will only give you 6.99% for the same basic loan scenario.
This all points to it being absolutely imperative to shop around instead of worrying about daily rate movement.
Shopping Rates Is More Important Than Tracking Rates
I’m all for tracking mortgage rates. I do it all the time. Daily in fact.
But I also run this mortgage blog and like to keep an eye on things for prospective home buyers and those looking to refinance an existing mortgage.
If you’re a consumer, tracking rates might be a waste of time, or a little too “in the weeds.”
There might actually be much more value or better ROI in shopping rates instead.
At the end of the day, mortgage rates are going to go what they’re going to do.
Whether that’s go up, go down, or move sideways.
And while us pundits can guess which way they’re going to go, or make fancy forecasts, they’re often going to be wrong.
Why? Because like anything else, it’s hard to make accurate predictions.
Very few expected the U.S-Iran conflict to break out, leading to rates climbing more than a full percentage point higher in the span of six months.
Yet here we are…facing the highest rates since early 2025 and the threat they could move even higher still.
Try out my new mortgage rate calculator to compare various rates side by side.
Control What You Can Control by Shopping Mortgage Rates Instead
Instead of worrying about rate movement from day to day, or month to month, control what you can control.
That means getting your house in order, whether it’s increasing your credit scores to obtain the best loan pricing or saving up a larger down payment to avoid mortgage insurance.
At the same time, no matter what rates are doing, the very best use of your time could be shopping rates.
Despite the 30-year fixed being the same exact loan offered by dozens and dozens of different lenders, it can be priced completely differently on any given day.
Take this screenshot above of a list of lenders offering a 30-year fixed on a typical home purchase.
The cheapest lender on the list was offering a quote of 6.12% with just shy of two discount points.
And the most expensive lender on the list was offering a quote of 6.99% with about 1.75 in discount points.
Same Loan, Different Price: Why Pay More?
This was for the same exact loan scenario, e.g. same down payment, loan amount, credit score, etc.
The end result is a monthly payment that is $200 cheaper (or more expensive) for the same exact mortgage.
It’s not like one comes with different features, like leather seats, or some other actual differentiator.
They’re all just plain old 30-year fixed mortgages with completely different prices.
Kind of like when you go to the grocery store and they have the store brand right next to the name brand product.
Because lenders market themselves and try to sell a commodity as if theirs is better for X, Y, or Z reason.
This means the best thing you can do is shop amongst lenders offering the same exact thing and find the cheapest, most competent one.
The last bit is important though. You need a lender that can actually close your loan. Because what good is a cheap loan that never funds?
(photo: Eden, Janine and Jim)
- Mortgage Rates Are Nearly 1% Apart Between Lenders Right Now - September 22, 2026
- Are Mortgage Rates Going Up or Down? - September 21, 2026
- Maybe Mortgage Rates Did Like the Fed Rate Hike After All - September 17, 2026